Compare Best Credit Cards in UAE
Compare 60+ credit cards from leading CBUAE-licensed banks in the UAE by salary, annual fee, rewards, and eligibility. Check the rewards, ...read more


Best credit cards with 0 Annual fee*


 Tanvi Pathak

What is Credit Card in UAE?
A credit card is a convenient way to pay for expenses, travel, online shopping, and emergencies. Note that you can use this card only up to the bank-approved credit limit, and you can repay later.
They are not only help you manage your monthly cash flows but also offer value-added benefits like cashback, air miles, reward points, travel privileges, and exclusive lifestyle protection.
Credit Cards in UAE: Key Facts
|
Question |
Answer |
|---|---|
|
What is a credit card? |
It is a payment tool that lets you make purchases on credit. You borrow money from the bank up to an approved credit limit and repay it on time to avoid interest charges. |
|
What is the minimum salary required? |
It varies by bank and the credit card you choose. Some basic cards require a minimum monthly salary of AED 5,000. |
|
Which credit card is the best? |
There is no single best credit card. The right one depends on your income, spending behaviour, and credit profile. |
|
What should I compare? |
Annual fees, reward structure, eligibility, income requirement, hidden charges, and welcome offers |
|
Does a credit card affect my credit score? |
If you use the card responsibly and repay the dues on time, your credit score improves. Being irresponsible with your repayments can lower the score. |
|
Where can I compare cards? |
You can compare multiple credit cards from the leading banks in the UAE on Paisabazaar.ae to find options based on your spending patterns and salary. |
Cashback Credit Card
ULTRACASH Mastercard Touch Card
TouchPoints Visa Infinite Credit Card
Which Credit Card is Best for You?
Rather than applying for multiple cards at once for different needs, find the right card. Analyse your spending patterns and find a card based on your budget, credit profile and specific needs. Check the recommended options and pick the best option for you.
|
User Need |
Recommended Card Type |
|---|---|
|
Frequent Traveller |
Travel credit cards |
|
Everyday Shopping |
Cashback credit cards |
|
Dining |
Dining rewards credit cards |
|
High Monthly Spending |
Premium reward cards |
|
Airport Lounge Access |
Travel credit cards |
|
Fuel Spending |
Fuel cashback credit cards |
|
No Annual Fee |
Free-for-life credit cards |
|
School Fees |
Education/school fee credit cards |
|
Monthly Bills |
Cashback credit cards |
Types of Credit Cards in UAE
There are several types of credit cards in UAE –

A travel credit card offers a range of benefits, like free miles, complimentary night stays, discounts on car rentals, and more.

These cards offer points that you can redeem for several expenses and products or services.

This type of card converts a portion of your spending into cash and credits it back to your card account.

These are Shariah-compliant cards that are free from Riba or Gharar (uncertainty).

Perfect for foodies, these cards offer discounts at participating restaurants.

These cards offer exclusive discounts at petrol pumps.
Why Compare Credit Cards on Paisabazaar.ae?
Paisabazaar.ae is more than just a financial marketplace platform! We present to you a platform where you get 60+ credit cards and other financial solutions tailored to your spending needs and budget. We aim to change your banking game in the UAE!
Here’s what it means to be a Paisabazaar.ae user!

Compare 60+ Cards
Compare card features, interest rates, reward structures, and annual fees for 60+ cards on one screen

Enjoy Personalised Recommendations
Get credit cards as per your profile and spending patterns using our integrated tools

Credit Cards for Every Spend Category
Use our in-built filters to find cards tailored for your specific needs, whether it’s travel, dining, cashback, no annual fees, shopping, or anything else

Convenience Assured
A platform suitable for everyone, be it a first-time applicant, a family member looking for cashback on everyday expenses, a frequent traveller, or a salaried professional

Cards from Top Banks
Enjoy flexibility to explore products from top CBUAE-licensed banks and finance companies on a single platform
Features & Benefits of a Credit Card in Dubai, UAE
| Loyalty Benefits |
Earn reward points with every purchase and redeem them for exclusive discounts. You can also convert your loyalty reward points into air miles to save on flight tickets with all partner airlines. |
|---|---|
| Airport Lounge Access |
Several credit cards in the UAE offer complimentary worldwide airport lounge access. Premium cards may also offer unlimited free access, plus a guest, making travel more rewarding. To access these services, complete a one-time registration with the service providers. |
| Exclusive Entertainment Offers |
Credit cards in UAE come with exclusive entertainment offers such as Buy1Get1 offers on movie tickets, discounts on theme parks and adventure sports, along with complimentary food and beverages. However, to avail of such offers, you may need to cross the minimum monthly spending threshold. |
| Dining Discounts and Offers |
As a cardholder in the UAE, you get exclusive offers on dining and restaurant expenses, including discounts and BOGO deals at various diners and coffee outlets. |
| Discounted Flight Tickets and Stays |
Using a card for flight bookings, you can save on flight tickets. Along with travel benefits, you get discounts on hotel bookings, including complimentary night stays, discounted fares, free upgrades, complimentary food, and more. |
| Travel Accident and Medical Insurance |
When you book a ticket with your card, you get complimentary worldwide travel medical and personal accident insurance. This multi-trip travel insurance covers each journey. |
| Convenient Financial Management |
With a credit card in UAE, enjoy interest-free days, easy payment plans, instant cash loans, utility bill payments, and online banking services all to help you manage your card account more effectively, anytime, anywhere. |
How Do We Compare Credit Cards?
We compare credit cards depending on key factors, including eligibility, annual fees, minimum monthly salary, fees, reward structure, and suitability for different spending behaviour. We review cards’ information regularly based on information provided by the issuing banks and available product information.
Here's what we consider:
- Eligibility
- Annual fee
- Cashback
- Airport lounge access
- Welcome offers
- Minimum monthly salary
- Rewards
- Travel benefits
- Fees
- Suitability by spending profile
Different Types of Credit Cards in UAE Offered by Paisabazaar
We host a range of credit cards for comparison on our portal. Top CBUAE-licensed banks issue these cards. To help you choose the right card, we have curated lists of top products across different card types.
Use our platform to compare cards based on your spending patterns, income, and credit history. Explore a range of cards, from free-for-life options to balance transfer cards, in one place on Paisabazaar.ae.
Air Miles Credit Cards in UAE
These cards suit frequent flyers and business travellers year-round. You can earn air miles with co-branded airline cards or standalone travel credit cards by spending in eligible categories, then redeem them for flights or hotel stays with qualifying airlines and hotel chains. Here are the top air miles credit cards to compare if you are a frequent traveller seeking the best value from your spending.
Top 5 Air Miles Credit Cards in UAE
|
Credit Card |
Annual Fee (AED) |
Minimum Salary (AED) |
|---|---|---|
|
HSBC Emirates Skywards Infinite Credit Card |
AED 2,625 |
AED 30,000 |
|
Citibank Citi Ultima Credit Card |
AED 3,000 |
AED 36,750 |
|
FAB Etihad Guest Infinite Credit Card |
AED 2,500 |
AED 30,000 |
|
Emirates NBD Voyager World Elite Credit Card |
Free for the 1st year |
AED 25,000 |
|
Emirates NBD Skywards Infinite Credit Card |
AED 1,575 |
AED 30,000 |
Airport Lounge Access Credit Card in UAE
A credit card with airport lounge access makes airport waits more comfortable by giving you access to exclusive lounges worldwide, where you can relax, work, dine, and travel stress-free, whether paid or complimentary. These cards partner with airport lounge networks to make that comfort possible. Check out the top options below, or compare more options on Paisabazaar.ae.
Top 5 Airport Lounge Access Credit Card in UAE
|
Credit Card |
Annual Fee (AED) |
Minimum Salary (AED) |
|---|---|---|
|
HSBC Emirates Skywards Infinite Credit Card |
AED 2,625 |
AED 30,000 |
|
FAB Etihad Guest Infinite Credit Card |
AED 2,500 |
AED 30,000 |
|
Liv Tamayaz World Credit Card |
AED 700 + VAT |
AED 15,000 |
|
FAB Travel Credit Card |
AED 1,500 |
AED 20,000 |
|
Emirates NBD Skywards Infinite Credit Card |
AED 1,575 |
AED 30,000 |
Balance Transfer Credit Card in UAE
If you have multiple high-interest credit card debts, a balance-transfer credit card can help you settle them. A balance transfer credit card offers a low introductory interest rate or a promotional 0% interest rate for a set period, typically 3 to 12 months. The card-issuing bank pays off your existing debts. You would need to repay the amount to your balance-transfer card issuer. These are the top balance transfer credit cards.
Top 5 Balance Transfer Credit Card in UAE
|
Credit Card |
Annual Fee (AED) |
Minimum Salary (AED) |
|---|---|---|
|
Citibank Citi Simplicity Credit Card |
Free for Life |
AED 5,000 |
|
Blue FAB Signature by Al Futtaim |
Free for Life |
AED 15,000 |
|
Ajman Bank ULTRACASH Mastercard Credit Card |
AED 500 |
AED 10,000 |
|
Blue FAB Platinum by Al Futtaim |
Free for Life |
AED 8,000 |
|
Ajman Bank BRight World Credit Card |
AED 1,500 |
AED 10,000 |
Apply Balance Transfer Credit Cards
Cashback Credit Card in UAE
Cashback credit cards return a percentage of purchases as cash, making everyday spending more rewarding. Banks offer cashback rewards on credit card purchases. However, cashback amounts vary by card and depend on categories, monthly caps, and minimum spending requirements. Here are the top cashback credit cards in UAE.
Top 5 Cashback Credit Card in UAE
|
Credit Card |
Annual Fee (AED) |
Minimum Salary (AED) |
|---|---|---|
|
ADCB 365 Cashback Credit Card |
Free for the 1st year |
AED 5,000 |
|
Liv Cashback Credit Card |
Free for Life |
AED 5,000 |
|
Al Hilal Cashback Credit Card |
Free for Life |
AED 5,000 |
|
Dubai First Cashback Card |
Free for the 1st year |
AED 5,000 |
|
ADCB Essential Cashback Credit Card |
Free for Life |
AED 5,000 |
Travel Credit Card in UAE
A good travel credit card helps you save on flights, hotels, and other travel costs. If you travel often, this card can help you manage travel expenses more efficiently. These cards also offer travel insurance coverage and other value-added advantages. The following are the top travel credit cards:
Top 5 Travel Credit Card in UAE
|
Credit Card |
Annual Fee (AED) |
Minimum Salary (AED) |
|---|---|---|
|
FAB Travel Card |
AED 1,500 |
AED 20,000 |
|
Emirates NBD Voyager World Elite Credit Card |
Free for the 1st year |
AED 25,000 |
|
Citibank Citi Ultima Credit Card |
AED 3,000 |
AED 36,750 |
|
HSBC Emirates Skywards Infinite Credit Card |
AED 2,625 |
AED 30,000 |
|
Emirates NBD Skywards Infinite Credit Card |
AED 1,575 |
AED 30,000 |
Cinema Offers Credit Card in UAE
Most banks in the UAE offer BOGO free movie tickets and discounts via credit cards. You also get discounts on food and beverages across major bank credit cards. That said, here are the top credit cards with cinema offers.
Top 5 Cinema Offers Credit Card in UAE
|
Credit Card |
Annual Fee (AED) |
Minimum Salary (AED) |
|---|---|---|
|
ADCB TouchPoints Visa Infinite Credit Card |
AED 1,050 |
AED 25,000 |
|
Liv Tamayaz World Credit Card |
AED 700 + VAT |
AED 15,000 |
|
Citibank Citi Rewards Credit Card |
Free for the 1st year |
AED 8,000 |
|
FAB Rewards Indulge Credit Card |
Free for Life |
AED 5,000 |
|
HSBC Live+ Credit Card |
Free for the 1st year |
AED 12,500 |
Apply Cinema Offers Credit Cards
Free For Life Credit Card in UAE
If you want to manage your finances smartly, choose a free-for-life credit card. It has no annual fee, making the rewards program even more appealing. Here are the best no-annual-fee credit cards.
Top 5 Free for Life Credit Card in UAE
|
Credit Card |
Annual Fee (AED) |
Minimum Salary |
|---|---|---|
|
ADCB LuLu Platinum Credit Card |
Free for Life |
AED 8,000 |
|
Liv Cashback Credit Card |
Free for Life |
AED 5,000 |
|
Al Hilal Cashback Credit Card |
Free for Life |
AED 5,000 |
|
Citibank Citi Simplicity Credit Card |
Free for Life |
AED 5,000 |
|
Dubai First Cashback Credit Card |
Free for Life |
AED 5,000 |
Apply Free for Life Credit Cards
Rewards & Offers Credit Cards in UAE
Rewards credit cards offer more value than basic credit cards because they provide clear benefits. These cards usually offer cashback, air miles, discounts, and other spending-based rewards. Here are the top rewards credit cards.
Top 5 Rewards & Offers Credit Cards in UAE
|
Credit Card |
Annual Fee |
Minimum Salary |
|---|---|---|
|
HSBC Cash+ Credit Card |
Free for the 1st year |
AED 30,000 |
|
ADCB TouchPoints Visa Platinum Credit Card |
Free for the 1st year |
AED 5,000 |
|
Citibank Citi Rewards Credit Card |
Free for the 1st year |
AED 8,000 |
|
FAB Rewards Indulge Credit Card |
Free for life |
AED 5,000 |
|
Emirates NBD SHARE Visa Signature Credit Card |
Free for life |
AED 12,000 |
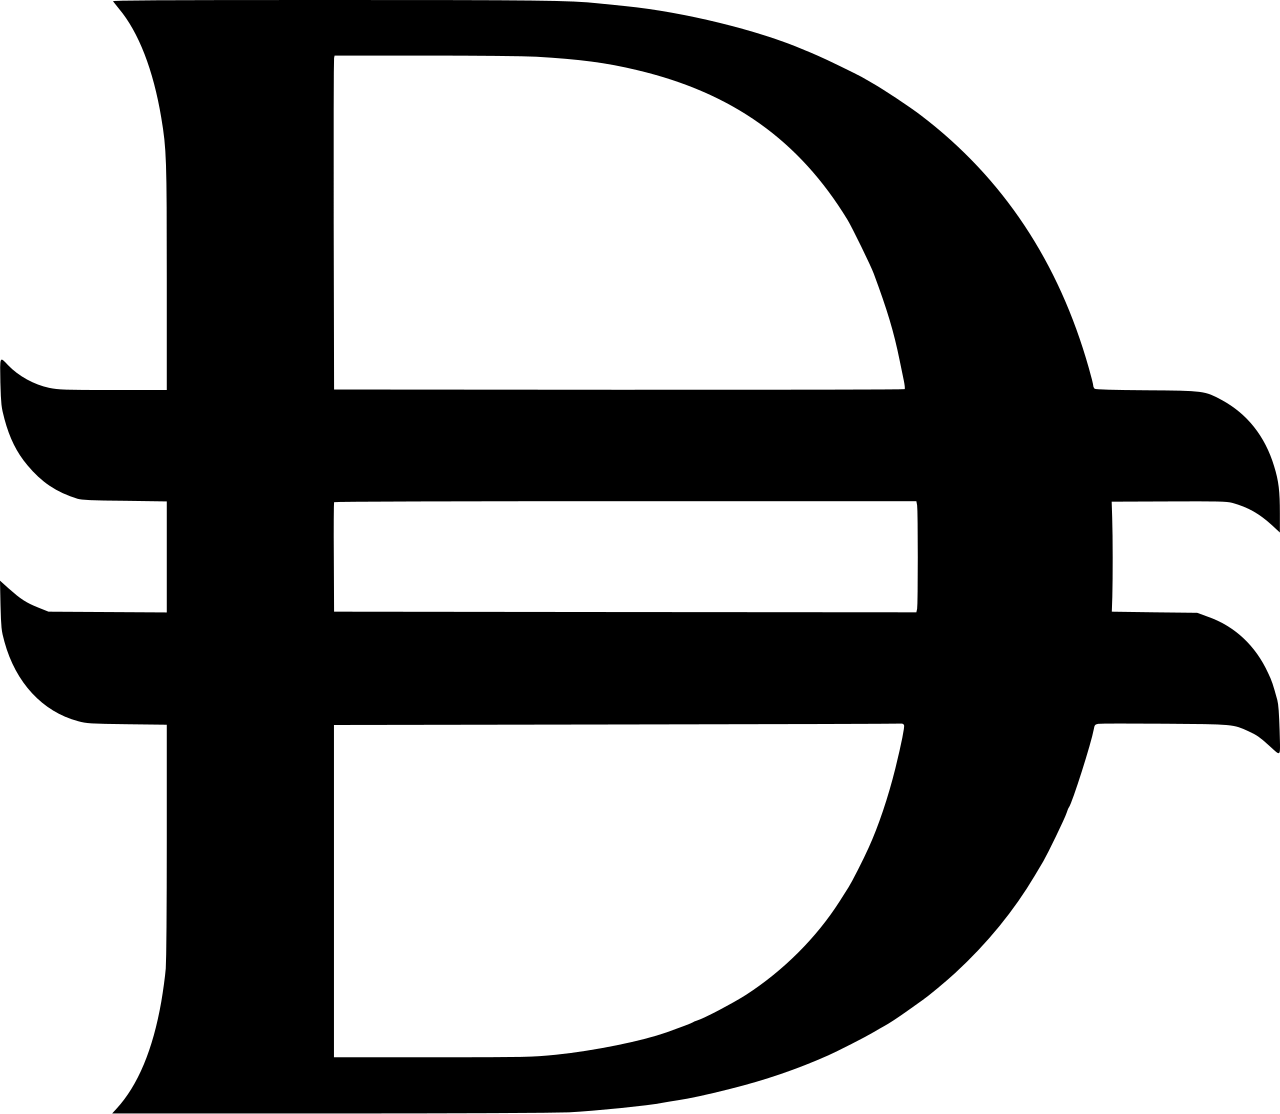 2500

We Offer Credit Cards by Salary in the UAE
Here are the best credit card options based on your salary.
Salary Bracket of AED 5,000 - AED 8,000
Suitable for - First-time credit cardholders, entry-level professionals, and individuals with a limited credit history
Salary Bracket of AED 9,000 - AED 12,000
Suitable for - People with stable employment, growing monthly expenses, people beginning lifestyle spending
Salary Bracket of AED 13,000 - AED 15,000
Suitable for - People who travel or dine regularly, high spenders
Salary Bracket of AED 20,000 + Salary
Suitable for - People with high salary brackets, people seeking premium lifestyle benefits, business travellers
Common Credit Card Charges You Should Know
While a typical credit card UAE comes with many charges, let’s take a look at some of the most important ones —
Annual Fee
Charged annually for the primary card
Retail Interest
Interest charged on purchases made using the card
Late Payment Fee
This charge is applicable if you don’t pay your bill on time
Card Replacement Fee
In case you replace the blocked existing card, you need to pay this charge
Supplementary Card Annual Fee
Charged annually for the supplementary card
Cash Advance Fee
It is charged when you take a cash advance on your card
Over Limit Fee
If your spending and interest exceed the prescribed limit, you need to pay this fee
International Transaction Fee
This charge is for using your card in foreign currencies
Interesting Facts about Credit Cards in UAE
 In the UAE, people carry about 2 to 3 credit cards Many prefer co-branded cards, while some go for standard ones The most preferred reward type is cashback The cards function uniformly across all the Emirates Visa and Mastercard cards are the most popular cards as they have widely accepted merchant and lounge networks
Pros and Cons of Credit Card in UAE
While cards are becoming increasingly popular, you also need to understand their pros and cons to use them mindfully and not fall into a debt trap.
Here are the pros and cons of credit card in UAE —
| PROS | CONS |
|---|---|
| . It offers more purchasing power | . Irresponsible use can lead to buying more than required |
| . You get access to a range of rewards | . Higher interest and a late payment fee if you don’t pay the bill on time |
| . You can track your expenses easily | . Not paying credit card bills can lead to a mountain of debt |
| . More convenient to carry than a stack of cash | |
| . Helps build a credit score and history |
Who Can Apply for a Credit Card in UAE?
Every bank has different eligibility requirements. However, to help you get a general idea, here are the standard criteria.
Minimum Age - 21 years Nationality - UAE nationals and residents Employment Status - Salaried or self-employed individuals Minimum Monthly Income - Usually starts at AED 5,000 per monthTips to Improve Your Credit Card Eligibility
Understand that a credit card in UAE can sometimes be complicated, especially if you are new to such cards and debt. Before applying, it’s important to know how to improve your chances of approval. After all, good usage can build a strong credit history and credit score.
Here are some tips to improve your chances of getting a better card in Dubai —
Don’t Miss Out on Any Card Payments - Missing out on card bill payments can harm your AECB credit score, which can hamper your chances of approval. To avoid this, set up auto debits for your bill payments.
Pay in Full Whenever Possible - While partial bill payment doesn’t harm your credit score, it does bring additional interest. This increases your repayment costs and traps you in a debt cycle.
Be Mindful of Your Credit Utilisation - You should keep your utilisation rate under 30% of your credit limit. Overusing your card shows you as a credit-hungry individual to lenders.
Avoid Unnecessary Spending - Overspending is a no-brainer if you have an available credit limit. However, this practice can land you in a tough-to-break debt cycle.
Don’t Apply for Multiple Credit Cards - Avoid applying for multiple cards in one go. This is because applications require a hard inquiry on your credit report, which harms your credit score.
Don’t Close Your Old Credit Cards - Closing your old cards reduces your total credit, increasing your credit utilisation ratio, and even removes a fair share of credit history. This can hurt your credit score.
Documents Required to Apply Credit Cards in UAE
Here is the list of documents required to apply for credit card online —
For Salaried Individuals
5 documents requiredFor Self-Employed Individuals
5 documents required


How to Choose the Right Credit Card in UAE?
The best credit card in Dubai, UAE is the one that aligns with your spending habits and income. With that said, here are some tips to find a card just right for you.

Understand Your Spending Habits

Compare the Rewards and Benefits
Use our Rewards Calculator to calculate the reward points you are eligible for!
Compare Fees and Interest Rates
Review the fine print for annual fee, late payment charges, interest rate, foreign transaction fee, and more. Make sure you go for a card with a simpler structure.
Review the Card’s Functionality
Check if your card is widely accepted at places that you prefer shopping at. Also, understand the card’s features, like credit limit, spending limits, adding alerts, or freezing the card if needed.
Make Sure Your Card Goes Beyond Welcome Bonuses
While sign-up bonuses are a tempting reason to pick a card, check the rewards on daily spending and other benefits for regular use.
Check the Application Process and Eligibility
Before applying, check the minimum income requirements, application approval time, credit score expectations, and more.
When to Apply for a Credit Card in UAE?
Ideally, you should apply for a credit card only if you have a stable, eligible income and valid documents. Timing also plays a key role in getting your application approved – say you got a bonus, a reasonable increment, or your credit score has increased.
That being said, we have listed some ideal scenarios that we largely vouch for when it comes to applying for a card.
When You Have a Stable Salary: At least 3 months of salary needs to be credited to your UAE bank account
Your Company is Listed: Approval comes easily if your employer is listed with the bank
You Meet the Minimum Requirements: If you have started earning a salary that meets the UAE’s banking guidelines, you can apply for a credit card
You Want to Build Your Credit Score: New to the UAE or just started earning? Get entry-level credit cards and build your credit first!
Common Mistakes to Avoid When Using a Credit Card in UAE
Here are some common mistakes to avoid when using a credit card in Dubai, UAE -

Financial Mistakes
Security and Management Mistakes
Card Usage Mistakes
Ans: It depends on the bank and card you're looking at. While many cards in the UAE set AED 5,000 as a minimum monthly income, some banks offer cards with lower thresholds or alternative eligibility routes. Your chances also come down to things like job stability, residency status, credit history and the documents you can provide. The best approach is to compare cards that specifically list requirements matching your salary before you apply.
Ans: It can, but not in a fixed, predictable way. Each application usually triggers a credit enquiry, and banks tend to notice when several show up close together, it can make them view you as a higher risk. That doesn't mean your score drops by some set amount every time. A better strategy is to check your eligibility against a card's requirements first and apply only where you're a reasonably strong match.
Ans: Banks typically look at your age, income, residency or employment status, credit history, and the documents you submit. There's no single income or age figure that guarantees a card, requirements differ from bank to bank and card to card, and meeting the basic criteria doesn't automatically mean approval, since each bank runs its own credit assessment.
Ans: Yes, many credit cards offer cashback, reward points, air miles and lifestyle perks like dining or travel benefits on specific cards for new cardholders. What you actually earn depends heavily on the card: rewards are often tied to specific spending categories, and there can be monthly caps, minimum spend requirements or exclusions. It's worth checking a card's reward structure against how you actually spend.
Ans: Yes, self-employed applicants can apply, though the process usually looks a little different from a salaried applicant's. Instead of a salary certificate, banks typically ask for bank statements, proof of business activity and other income-related documents to assess how stable your earnings are. Approval still comes down to your overall financial profile and credit history, and exact requirements vary from bank to bank.
Ans: Yes, credit cards are widely used for online shopping, subscriptions and other digital payments in the UAE. Most banks add layers of protection like OTP verification and transaction alerts to flag unusual activity. That being said, no system makes online payments completely risk-free but it still helps to stick to trusted websites, check your alerts regularly and never share your card details, PIN or OTP with anyone.
Ans: Being new to the UAE doesn't rule you out, but it can narrow your options. Some banks observe your local income, your employer, or an existing banking relationship, such as a salary transfer account, more heavily for newer residents. You may also need to show proof of residency and employment. Cards aimed at applicants with an established UAE income tend to be the easiest to qualify for early on.
Ans: A few things matter such as, the minimum salary required, the annual fee or any interest/profit related charges. Other than that, there also rewards & cashbacks on certain cards that provide travel perks, airport lounge access and welcome bonus.Fees and eligibility criteria are worth checking too. Then match all of this against how you actually spend, frequent travellers may value miles and lounge access, while everyday spenders often get more out of cashback.
Ans: Yes, you can hold more than one, as long as you meet each issuer's eligibility and approval criteria. Whether it's a good idea for you depends on how well you can manage it, think about your combined credit limits, any outstanding balances, multiple annual fees and keeping track of different due dates. Used responsibly, with on-time payments, multiple cards aren't inherently a problem; the risk mainly comes from losing track of them.
Ans: Banks set your limit based on a mix of factors such as your income, existing loans or financial commitments, credit history, how reliably you've repaid debt in the past, and your overall credit exposure. Internal policies also play a role. A higher salary can support a higher limit, but it isn't a guarantee, the final number depends on the full picture the bank sees, and it can vary even between applicants with similar income.
Ans: Timelines vary quite a bit depending on the bank and card. Some applications get an instant decision, while others need extra verification and can take several working days, especially if documents are incomplete. Keep in mind that approval and card delivery are two separate steps, even after you're approved, the physical card can take a bit more time to arrive.
Ans: Not having a credit history doesn't automatically mean rejection, but it does affect which cards are realistically available to you. Some banks offer secured credit cards, where a fixed deposit backs the credit limit, a common way in for first-time applicants. Others have separate criteria for people with limited history. Whichever route you take, using the card responsibly and paying on time is how you start building credit from there.
Ans: The minimum payment is whatever amount your issuer specifies on your monthly statement, it's not a fixed 5% across all UAE cards, and it can shift depending on your card and outstanding balance. Paying just this amount keeps your account from falling behind, but it doesn't clear your balance, and finance charges typically keep accruing on whatever's left. To avoid those charges, it's best to pay the full statement amount by the due date, check your Key Facts Statement for the exact terms on your card.
Ans: There's no universal answer, it depends on how you spend and manage money. Credit cards offer convenience, rewards and purchase protection, and they're accepted almost everywhere in Dubai. Cash is easier for sticking to a budget and comes in handy at the few places that don't take cards. If you lean on a credit card, just be aware of any fees involved and make sure you can pay off the balance on time.
Ans: The best credit card in UAE largely depends on your salary, spending patterns, and lifestyle needs. For example, a cashback card is ideal for your daily expenses like groceries and fuel. A travel credit card, on the other hand, is the right option only if you are a frequent flyer.
Ans: Salary transfer isn't required to get a card. To check your repayment capacity, banks use the IBAN code of your active bank account. Although banks prefer salary credit for underwriting, most only need your IBAN code to check your cash flow. Read the terms and conditions before applying.

More From Credit Cards
- Recent Articles
- Popular Articles
 Last Updated : 15 Sep 2026Best Credit Card for Noon Supermarket in UAE 2026Best Credit Card for Noon Supermarket in UAE 2026 – Compare top cards, cashback offers, rewards and benefits to maximize savings on your Noon grocery purchases.
- Last Updated : 08 Sep 2026Best Credit Cards for Carrefour in UAE 2026Compare the top credit cards for Carrefour shopping in the UAE. Discover cards offering up to 8% back in SHARE points, cashback, and 0% installment plans.
 Last Updated : 27 Aug 2026Best Credit Cards for AED 30000 Salary in UAE (2026)Compare premium Visa Infinite & Mastercard World cards for AED 30K salary in the UAE. Maximize Skywards miles, valet parking, airport lounge access, and cash rewards.
 Last Updated : 26 Aug 2026Best Credit Cards for LuLu Hypermarkets in UAEDiscover the top credit cards for LuLu Hypermarket shoppers in the UAE. Compare top cards and high-cashback grocery options to earn up to 10% back on your daily purchases.
- Last Updated : 12 Aug 2026Best Credit Cards for AED 25,000 Salary in UAE (2026) – Top Rewards & TravelExplore the best UAE credit cards for an AED 25,000 monthly salary. Compare top premium cashback, travel, and lifestyle cards from top banks in UAE.
 Last Updated : 05 Aug 2026Best Credit Card for AED 15,000 Salary in UAECompare the best credit cards for AED 15,000 salary in the UAE. Discover top cashback, travel miles, lounge access, and zero annual fee cards